Delhi woman loses Rs 77,114 in unauthorised transactions after issues with her mobile phone delay SMS alerts, she alerts bank but gets no refund; consumer commission orders bank to pay Rs 70,084 with 7% interest and Rs 25,000 as compensation and litigation expenses
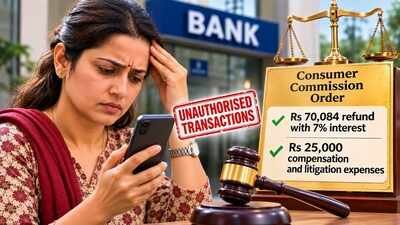
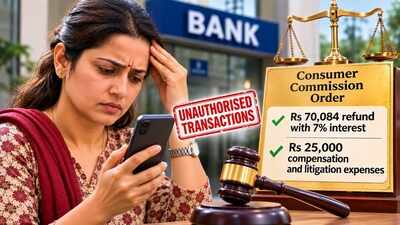
What happens if you lose money from your bank account due to unauthorised transactions? Is the bank liable to pay you? In one such case a Delhi-based woman took her bank to court after losing money in three online transactions in 2016 that she said she had not authorised.Accusing her of deficiency in service, the woman sought a refund of Rs 2,28,839, along with 18% interest, ECS charges, revival penalties, compensation for mental agony and Rs 25,000 towards litigation expenses.The bank, however, maintained that customers were responsible for any leakage of their one-time passwords (OTPs) and card details. The Delhi Consumer Disputes Redressal Commission ultimately ruled in the woman’s favour.
What the case is about
The woman claimed that three unauthorised online transactions, carried out on July 4, July 5 and July 9, 2016, resulted in a total of Rs 77,114 being deducted from her bank account.She said she was experiencing problems with her mobile phone during that period and was consequently unable to access the internet. She also alleged that no SMS alerts were received when the transactions took place.According to Varsha, she received a delayed SMS notification on July 10, 2017, following which she immediately approached her bank and requested that all transactions in her account be blocked. She also filed a police complaint at the police station.The woman further alleged that the unauthorised debits led to ECS penalty charges being imposed by the bank and affected her mutual fund investments. She also said her life insurance policy lapsed and had to be revived after she paid the applicable penalty charges.As the bank did not return the money lost in the disputed transactions, the woman sent it a legal notice dated May 2, 2018.In its response before the commission, the bank said it “is not responsible for transfer of funds to any third party.According to an ET report on the judgement, the bank also argued that the account holder had not received the OTPs because her mobile phone was not working. “The leakage of OTP and the card details is the responsibility of the card holder,” it stated, seeking dismissal of the complaint.
Why did the Consumer Commission rule in favour of the bank account holder?
The Consumer Commission referred to an email sent by the woman on 10 July 2016, in which she had provided details of the fraudulent transactions carried out on July 4, 5 and 9.The email stated: “Rs 5,000 was used for unauthorised transaction on 04.07.2016, Rs 2,000 on 05.07.2016 and Rs 70,084 on 09.07.2016.”The commission also relied on the RBI circular titled ‘Customer Protection-Limiting Liability of Customers in Unauthorized Electronic Banking Transaction’. The circular provides for zero liability for customers when an unauthorised transaction occurs due to fraud, negligence or deficiency on the bank’s part, or because of a breach by a third party.After a legal battle lasting nearly a decade, the commission ruled in the woman’s favour, holding the bank deficient in service. It directed the bank to refund the amount she had lost in the fraudulent transaction dated July 9, 2016.The bank has been ordered to pay the woman Rs 70,084, along with interest at 7% from the date of the transaction until the amount is paid. The bank must also pay her Rs 20,000 as compensation and Rs 5,000 towards litigation expenses.Two factors proved crucial to the woman’s case: reporting the unauthorised transactions promptly and supporting her complaint with documentary evidence.Anuj Dave, Practice Head (Ahmedabad & Mumbai) at Clavius Legal, told ET that the woman had informed the bank about the disputed transactions. She had also filed a police complaint and submitted documentary evidence in support of her case.The bank, meanwhile, alleged that the customer’s banking credentials had been compromised but failed to produce documentary evidence to establish negligence on her part.“The fundamental legal principle is that a bank cannot escape liability merely by alleging that an OTP or banking credentials were compromised. Under the RBI’s customer-protection framework relied upon in the order, the burden of establishing customer liability rests on the bank,” Dave said.